The Million Dollar HSA · By Brian Rayhack
The most powerful retirement account may be one that most people completely overlook.
Health Savings Accounts, or HSAs, are often treated like simple spending accounts for doctor visits and prescriptions. In reality, an HSA can become one of the most valuable accounts in a long-term financial plan.
The only account with a triple tax advantage
Tax-deductible contributions
Contribute pre-tax dollars and lower your taxable income today.
Tax-free growth
Invest your balance and let it compound with no tax on the gains.
Tax-free withdrawals
Pay for qualified medical costs without paying a dime in tax.

The Book
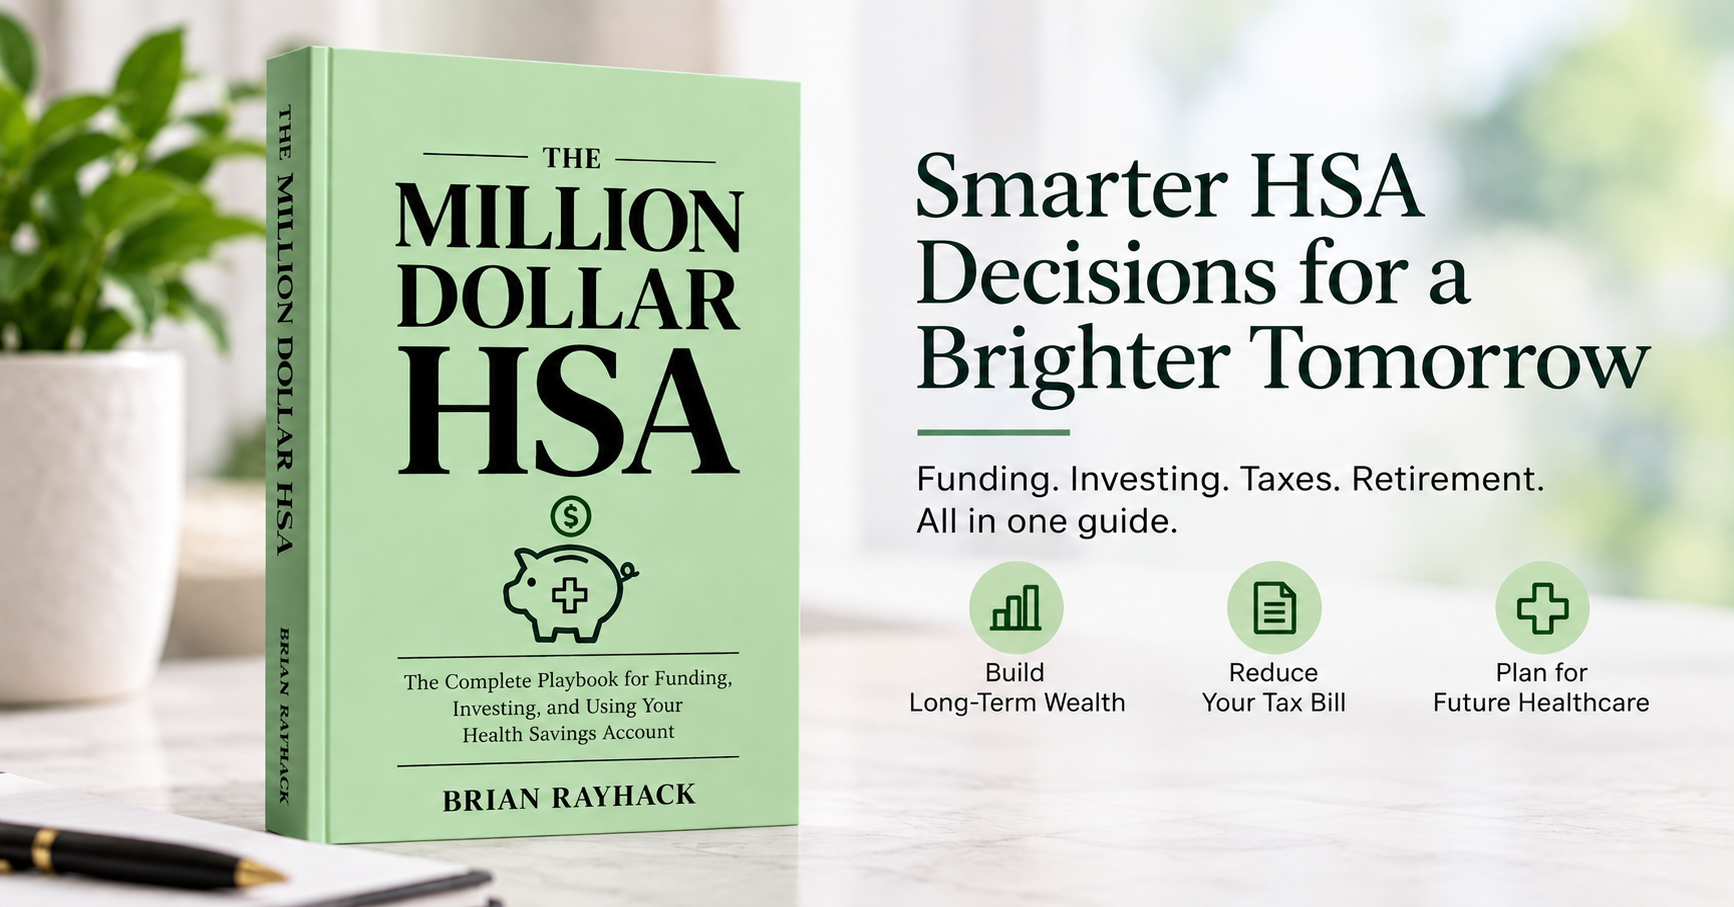
The Million Dollar HSA
In The Million Dollar HSA, Brian Rayhack whose own HSA has grown past the $1 million mark, shows how a Health Savings Account can become part of a long-term investing and retirement strategy, not just a place to save for medical bills.
Written for both new and experienced HSA owners, the book covers funding, investing, tax advantages, delayed reimbursement, and the decisions that make the biggest difference over time.
Available in Kindle, paperback, and hardcover.
Who it’s for
For anyone ready to think differently about their HSA.
You don’t need a big balance or a finance background. Whether you’re just getting started or you’ve been contributing for years, The Million Dollar HSA gives you a practical framework for one of the most misunderstood accounts in personal finance, and shows you what it can do once you stop treating it like a checking account for copays.
A clear framework for one of the most underappreciated accounts in personal finance.
You’ll learn how to:
Reduce taxes with every eligible contribution
Choose an HSA custodian that actually lets you invest
Invest an HSA for long-term, tax-free growth
Turn qualified medical expenses into future tax-free withdrawals
Avoid common mistakes that limit the value of an HSA
Think about healthcare costs as part of a broader retirement plan
A window that closes at 26, and most families never open it.
An adult child covered on a family health plan may be able to open their own HSA, with their own full family contribution limit, completely separate from their parents’. They can fund it themselves, family can help, or both. Either way, the account and every decade of tax-free growth in it belongs to them.
The day they turn 26, the opportunity is gone for good.
Read the Pre-26 Play™For educational purposes only. Not a recommendation or a projection of actual results.
Free tools
Plan your HSA with two free calculators.
Estimate the potential tax savings of a contribution, then see how an invested HSA could grow over time.
Tax Savings
HSA Tax Saving Calculator
Estimate the potential federal, payroll, and state tax savings from making an HSA contribution.
Investment Growth
HSA Investment Growth Calculator
See how an invested HSA could grow over time based on your balance, contributions, and time horizon.
Start your HSA strategy
Read the book. Rethink your HSA.
Written by Brian Rayhack, creator of The HSA Playbook and @thehsaguy on Instagram. Discover a practical, straightforward way to understand the long-term potential of your Health Savings Account.